01
Origination
Know on day one.
Landworth’s AVM and comparable evidence, with borrower and property checks from PEP and sanctions screening to flood risk. The system flags what needs a closer look.
Automation and intelligence for UK property lenders. Regulated by RICS (opens in a new tab).
Second charge, Bridging, Development, Portfolios
Valuations
Due diligence
Planning
Origination

Regulation
Please use this one instead.
Dated March 2026
| Today | With Landworth |
|---|---|
| A first view of a deal in days. | A first view in hours. |
| A valuation PDF, Companies House tabs and broker emails. | One case file, every fact linked to its source. |
| Policy applied from memory. | Policy applied to every deal, exceptions flagged. |
| The back book revalued when someone has time. | The whole book revalued and re-checked on demand. |
Send us a case. Landworth reads every sale, company and charge behind it, checks the deal against your policy and returns one case file, with every figure linked to its source.
You ask
Screen 14 Orchard Close: a £125,000 second charge behind a £260,000 first charge.
 Landworth returns
Across the life of the loan, alongside your team and on the systems you already run. We don’t lend or compete for your deals.
Know on day one.
Landworth’s AVM and comparable evidence, with borrower and property checks from PEP and sanctions screening to flood risk. The system flags what needs a closer look.
Three borrowers each request £350k. Each puts their property’s value at £530k.
At a maximum 70% LTV, each property needs to be worth at least £500k.
Bar: valuation range.
Dot: central estimate.
Case 1
Our central estimate is £20k above the required value.
Case 2
Central estimate £25k short. Upper estimate fits.
Case 3
Even our upper estimate is £25k below the required value.
Property value (GBP)
Illustrative valuation checks. Other underwriting checks still apply.
Work green first, then amber. Red can wait.
Every fact, with its source.
Comparables, company and ownership connections and source-linked findings, in one case file your underwriters can interrogate.
See it on a live caseSee the whole book, and what’s changing in it.
Value your property portfolio and run due diligence across your back book. Compare original valuations with automated estimates and flag properties or borrowers for review.
Companies House records help build your borrower list and inform the checks.
Wherever your team already works.
Bring property and financial intelligence into your email, CRM, spreadsheets or bespoke systems. Our engineers scope and build the connection around the way your team works.
All Landworth features are available via API, with MCP access to follow.
We evaluated several valuation providers, and Landworth clearly stood out. Their comparable evidence and ability to tailor the solution to our lending requirements mean we make faster, more confident decisions.
Three screens from the platform lenders use today. One case file, three kinds of intelligence.
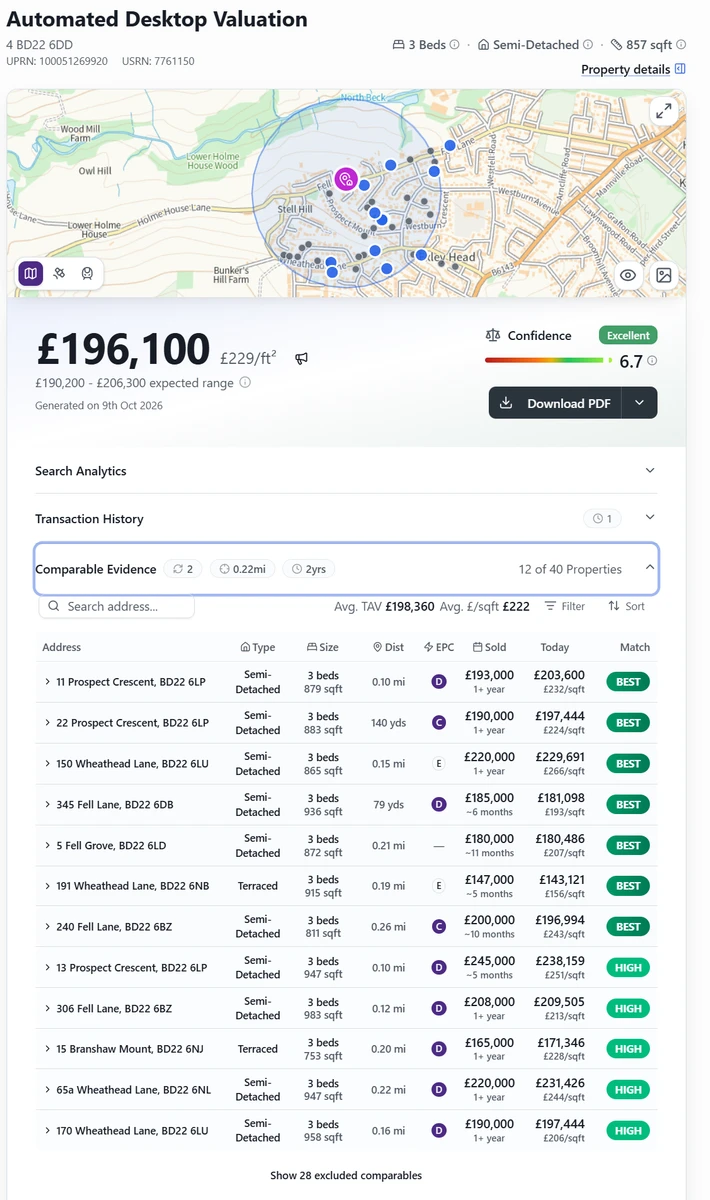
The estimate, its expected range and a confidence score above twelve comparables, each adjusted and rated, on one screen.
Landworth’s AVM, in use since 2018, with more than 9,000 registered users on our self-service platform.
A borrower’s appointments, ownership and control relationships and the companies behind them, with registered numbers and every finding linked to its source.
Built on Companies House records, read for every case.
Original values beside today’s estimates for every property in the book, with the ones that need a closer look flagged.
Automated portfolio valuations, available today.
Financial data, valuation expertise and engineering, working together around your lending decisions.
Landworth’s AVM brings together several valuation methodologies, using checked property data and comparable evidence. An automated valuation agent works through the evidence, compares the methods and explains the estimate, its assumptions and any gaps for your team to review.
Landworth brings together company records, ownership and directorships, registered charges, adverse media, and PEP and sanctions screening, with links to the underlying sources. Property checks include flood risk. Your team can review potential matches and follow the connections behind a case. We agree the scope around your lending policy; your underwriter retains judgement and sign-off.
We can start with one case alongside your existing arrangements. Upload documents or reports from any provider and we’ll extract the key facts and figures, adding the original documents and extracted information to the deal’s case file. We bring that evidence together with property and borrower checks and expert support around your lending policy.
Automated appraisals are desktop analyses with comparable evidence and source links, not formal RICS valuations. Landworth is regulated by RICS, which requires professional indemnity insurance. How cover applies depends on the output. Where your policy requires a formal valuation, we help you instruct one. The signing valuer is responsible for it, and we agree the scope, reliance and cover with you before instruction.
Yes. Initial screening helps your team identify which cases warrant further work, alongside the valuation your funder requires. Under NDA, we can provide a methodology note and work with your funder’s compliance team to support their review and sign-off.
Landworth sits on top of the tools you already use, so your loan origination system, CRM and broker portal stay in place. Our engineers work with your team on the first connection. Customer platform data is processed and stored within the UK and EEA, and is never used to train third-party models.
We agree a pilot and onboarding plan around your team and systems. We start with a conversation about what slows your team down, show you a sample on one of your own deal types, then run a pilot on your actual deal flow. No upfront commitment is required.
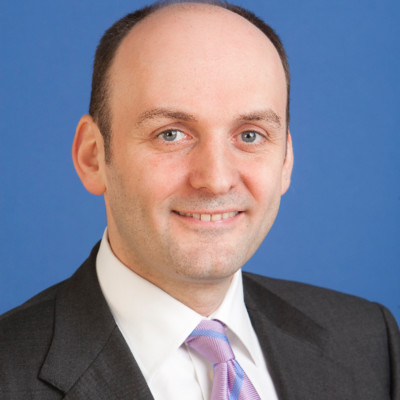
“Every loan comes down to three questions: what it’s worth, who’s behind it, and where it’s going. We built Landworth to answer all three.”
Paul ChapmanFounder & CEO, Landworth
Work through a case with Paul Chapman, Landworth’s founder. A free 30-minute conversation about the evidence, the sticking points and a useful next step.
Rebuilding how the UK lends
against property. Deal by deal.
 Claude